Buying Your FIRST Home? Read Below to Get All of the Details.
Heads up… This is a LONG one, but we wanted to provide you with something in-depth, so you feel educated, and prepared, which is one of our most important pillars at Maria & Jen Collective.
1. Start with a Real Conversation with Us (or another trusted Realtor ®, boo!)
This really is the most important first step, even before you tour a home! In fact, due to our Realtor® code of ethics and best practices, we can’t actually tour you through a home until you are under a signed Buyer Agency Contract.
Here’s what we will cover in our first meeting together, it’s one you won’t want to miss:
- Your goals (starter home? long-term home? investment potential?)
- Financing and budget
- Timeline
- Lifestyle and location wants and needs, we’ll set you up on a custom search!
This is where we talk honestly about today’s market conditions, what’s realistic, and what strategy makes sense for you.
Here’s something we value most, after this meeting you’ll feel a sense of clarity and excitement instead of confusion and worry.
2. Get Financing in Order
Planning to take out a new mortgage? Or planning to pay with cash on hand? Either way, we’ll need to have proof that you are able to secure the home financially.
- A pre-approval or a proof of funds (if you are paying with cash) is your green light.
Why this matters:
- Sellers take you seriously
- You know your real numbers
- You can move fast when the right house hits
Tip: Don’t over obsess over interest rates. They are cyclical and rise and fall given the national debt, something you have no control over. What you can control is making sure you are purchasing something in your current budget that doesn’t make you house poor.
There is a saying in real estate, “marry the house, date the rate”. This means that when the interest rates come down, and/or you’ve hit over 20% of equity in your home, re-financing might be a great option! There are strategies to buy smart now and refinance later if the opportunity presents itself.
3. Understand Your Full Costs
First-time buyers often focus only on the down payment. But you should also plan for:
Closing costs (typically 2–5% of purchase price)
- Earnest money deposit
- Inspection costs
- Appraisal
- Moving expenses
- Immediate updates or repairs
There are also first-time buyer programs and local incentives that can help, especially here in growing markets like West Michigan. This is why shopping for the right local lender for you is so important. Ask us to connect you with our favorite trusted local lenders to get started with the right foot forward.
Now the fun part.
4. Go House Hunting with a Strategy
But it’s not just about walking through pretty homes. We look at:
- Condition (this matters more than ever)
- Roof, furnace, foundation age
- Resale potential
- Location trends
- Days on market (negotiation leverage)
You will hear us say two very important statements:
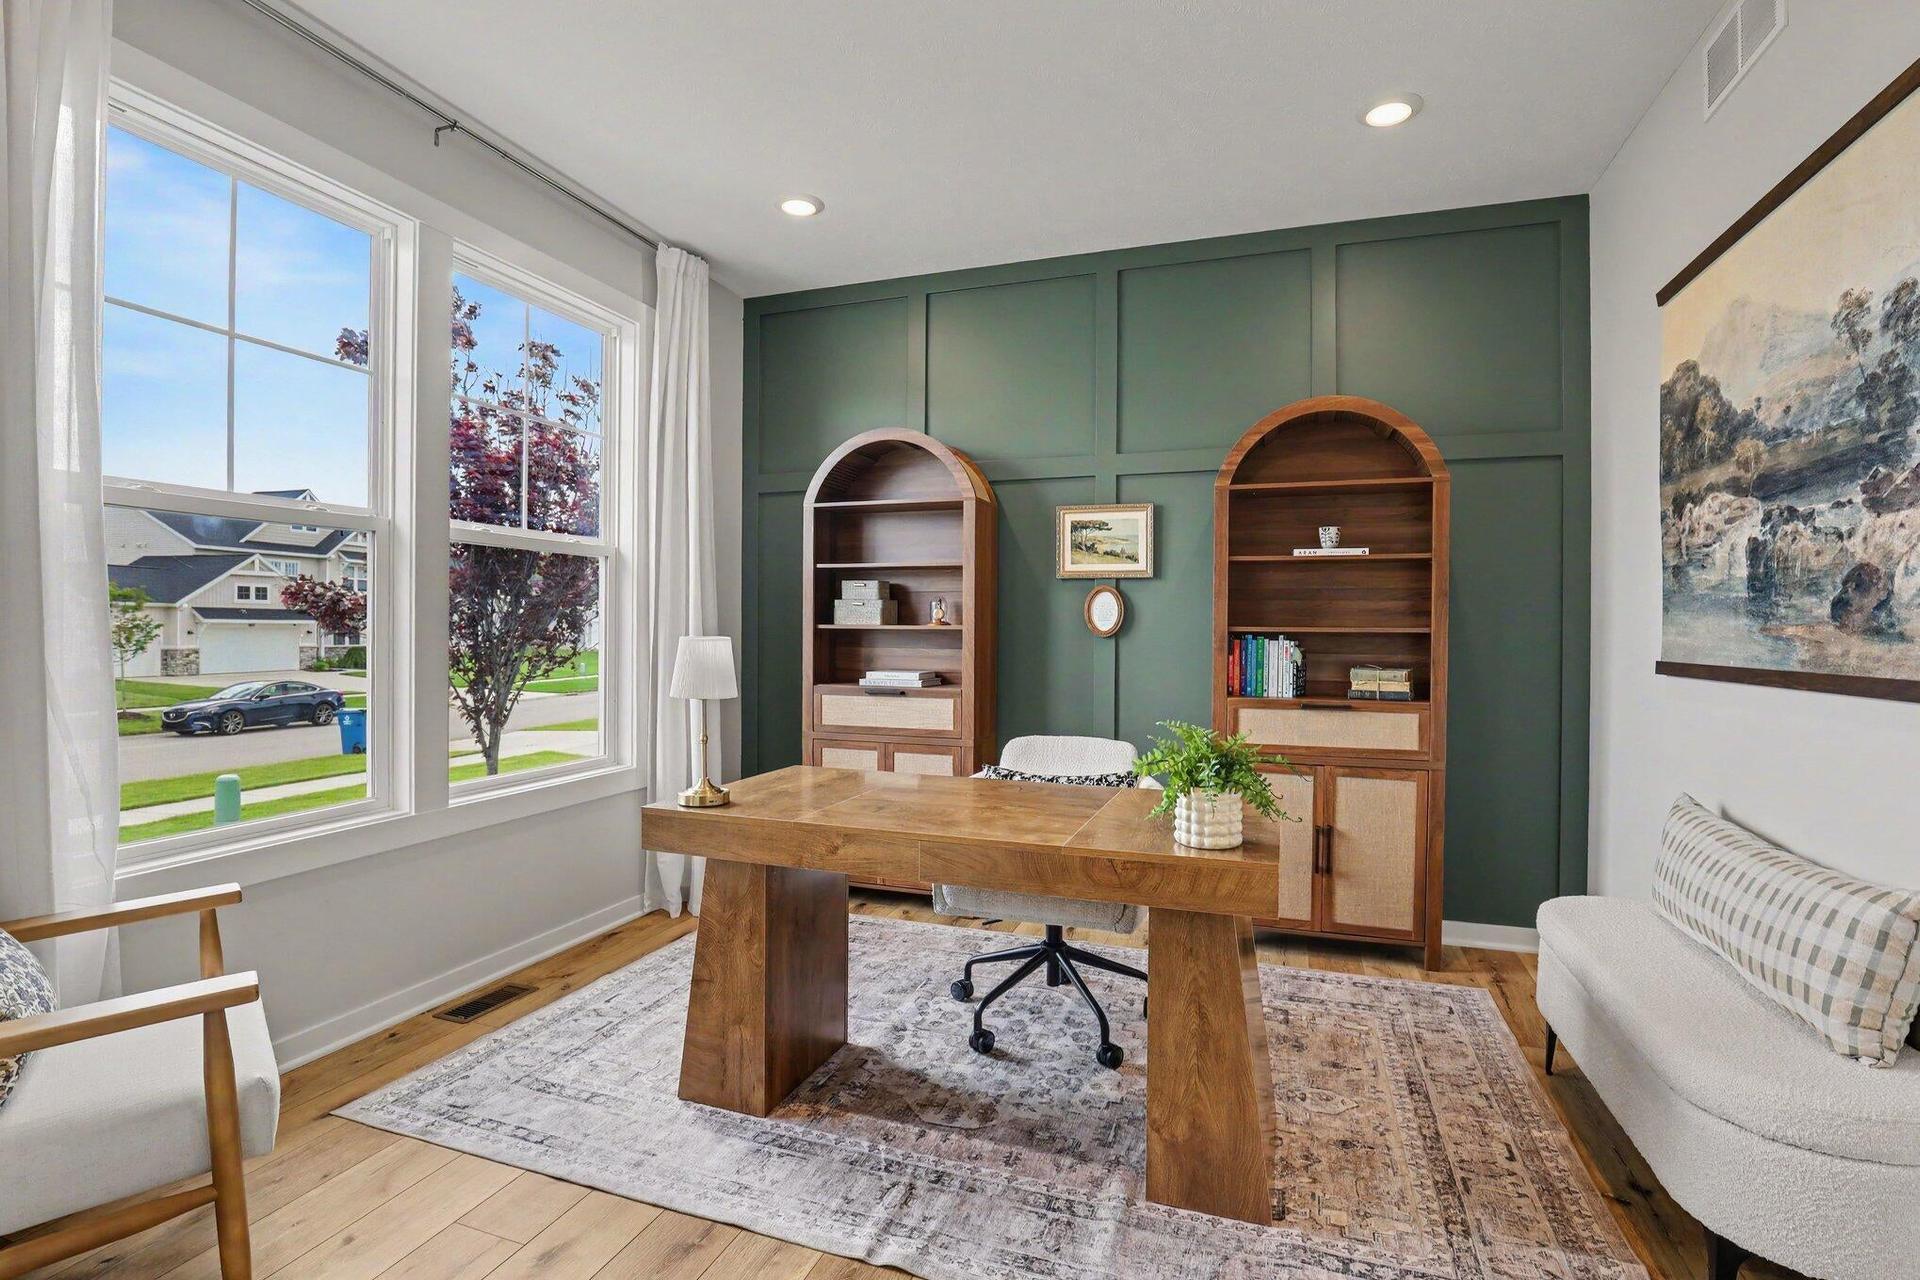
“Look past the décor!”
“We’re looking for good bones.”
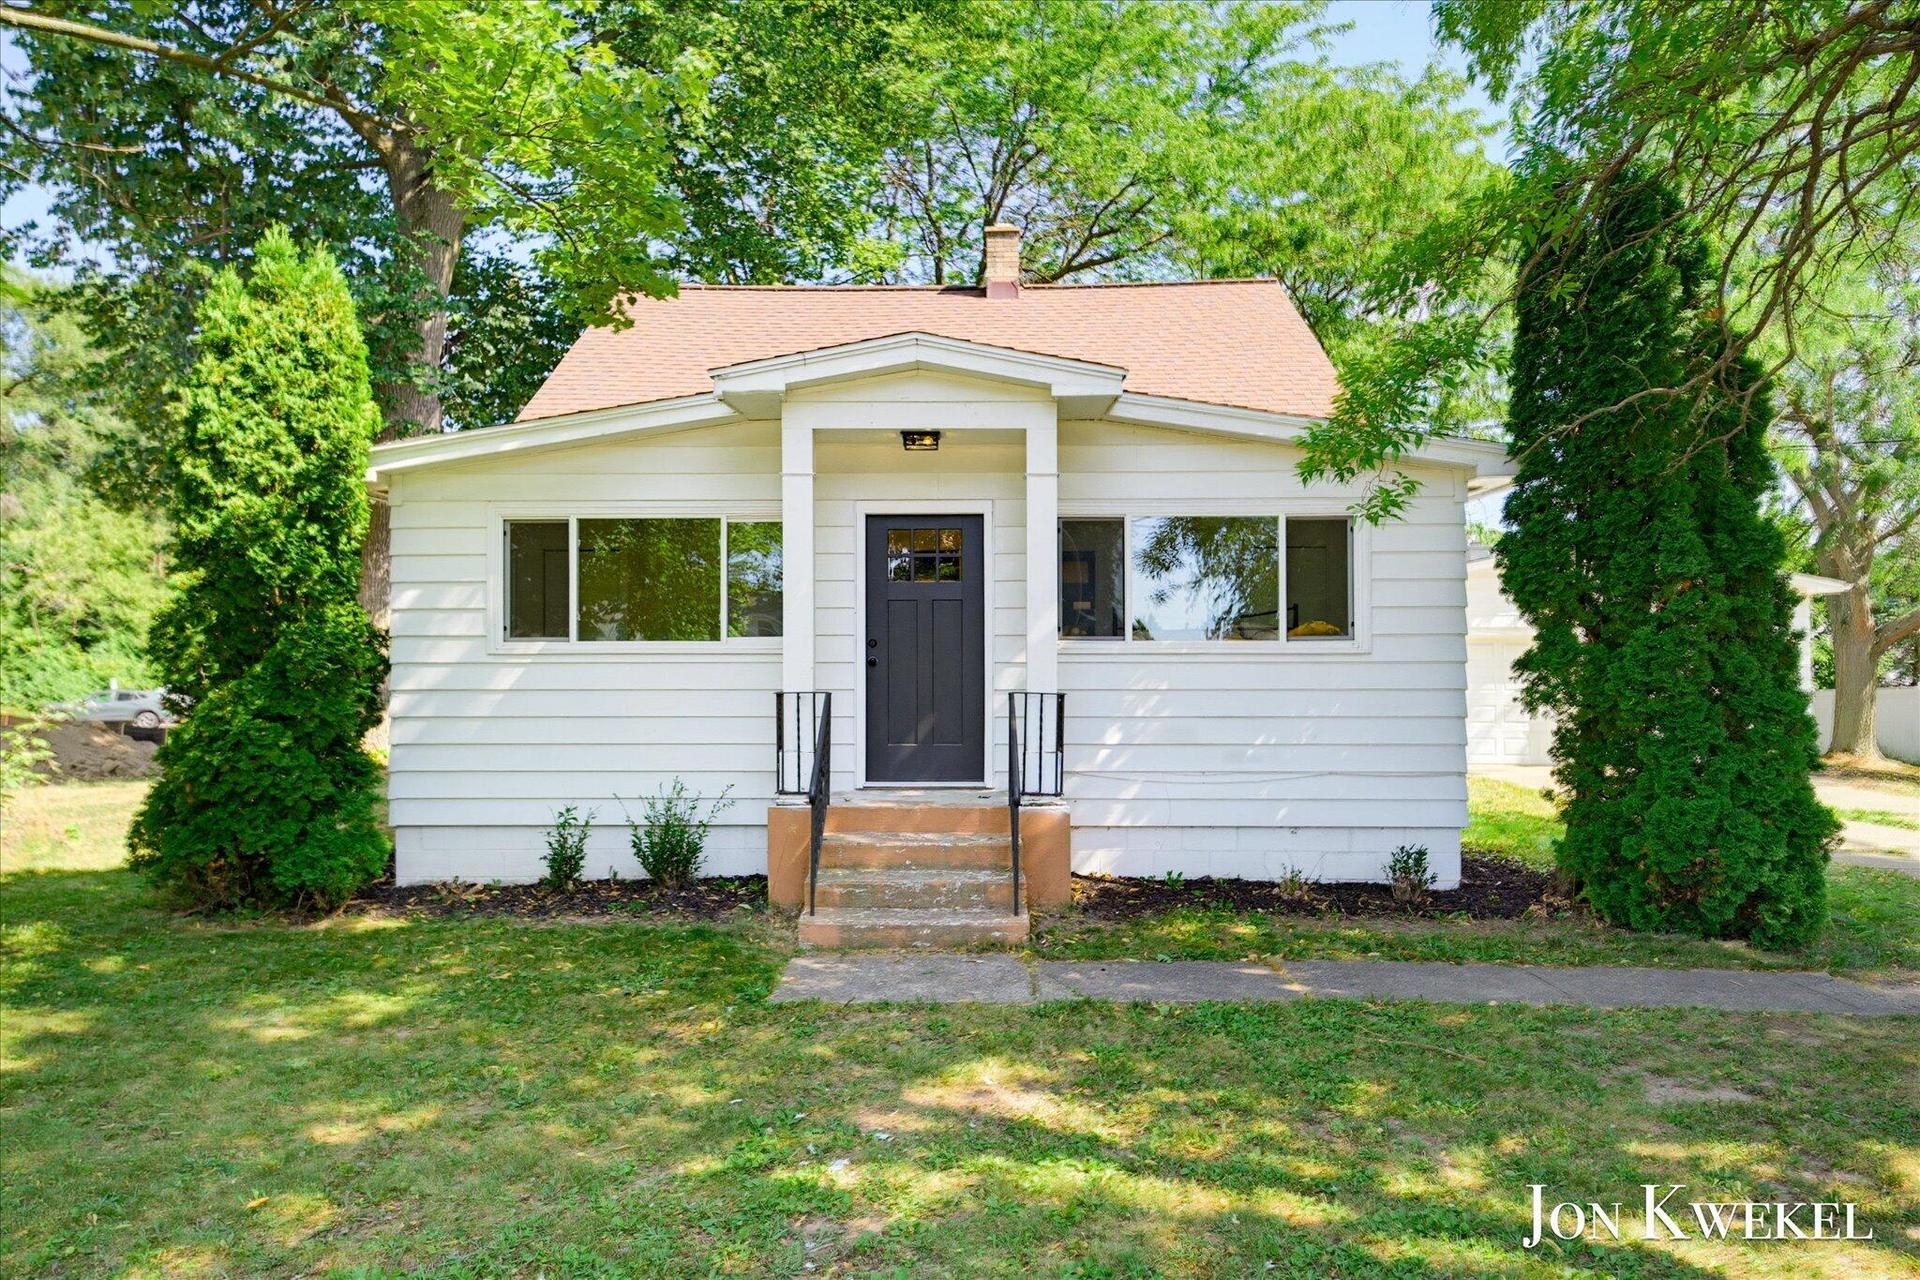
Homes that “look” pretty with cute décor and fun new paint colors, but have a 20+ roof and a wet basement are cause for concern. Look past the décor, it usually doesn’t come with, and instead focus on the conditional items that are impossible or expensive to change.
Sometimes the best opportunities are homes that have been sitting for 2+ weeks, OR another big Maria & Jen Collective secret…. Look during the holidays! That’s where negotiation power can shift in your favor.
Buying isn’t about winning a house. It’s about making a smart investment that has easy resale in any real estate market.
5. Write a Strong Offer that is Well Communicated
An offer is more than a price. West Michigan is a relationship driven market. A small percentage of the real estate agents in our association handle the majority of our transactions. Relationships matter. We have served for our 15 years combined in our market and are active alums of leadership academies and committees within our association. We also have several local and national designations, awards and credentials. We don’t say this to beat our chests, we say this because we have a lot of experience in knowing what works in getting you an accepted offer.
Communication, attention to detail and that “midwestern nice”, really matters. We will help you to structure your offer so it fits your needs while also being attractive to a Seller.
Things we’ll discuss:
- Purchase price
- Financing and lender relationships
- Inspection terms
- Appraisal gap strategy
- Possession timing
- Contingencies
This is where experience matters. It’s about protecting you while making your offer stand out.
6. Inspection & Due Diligence
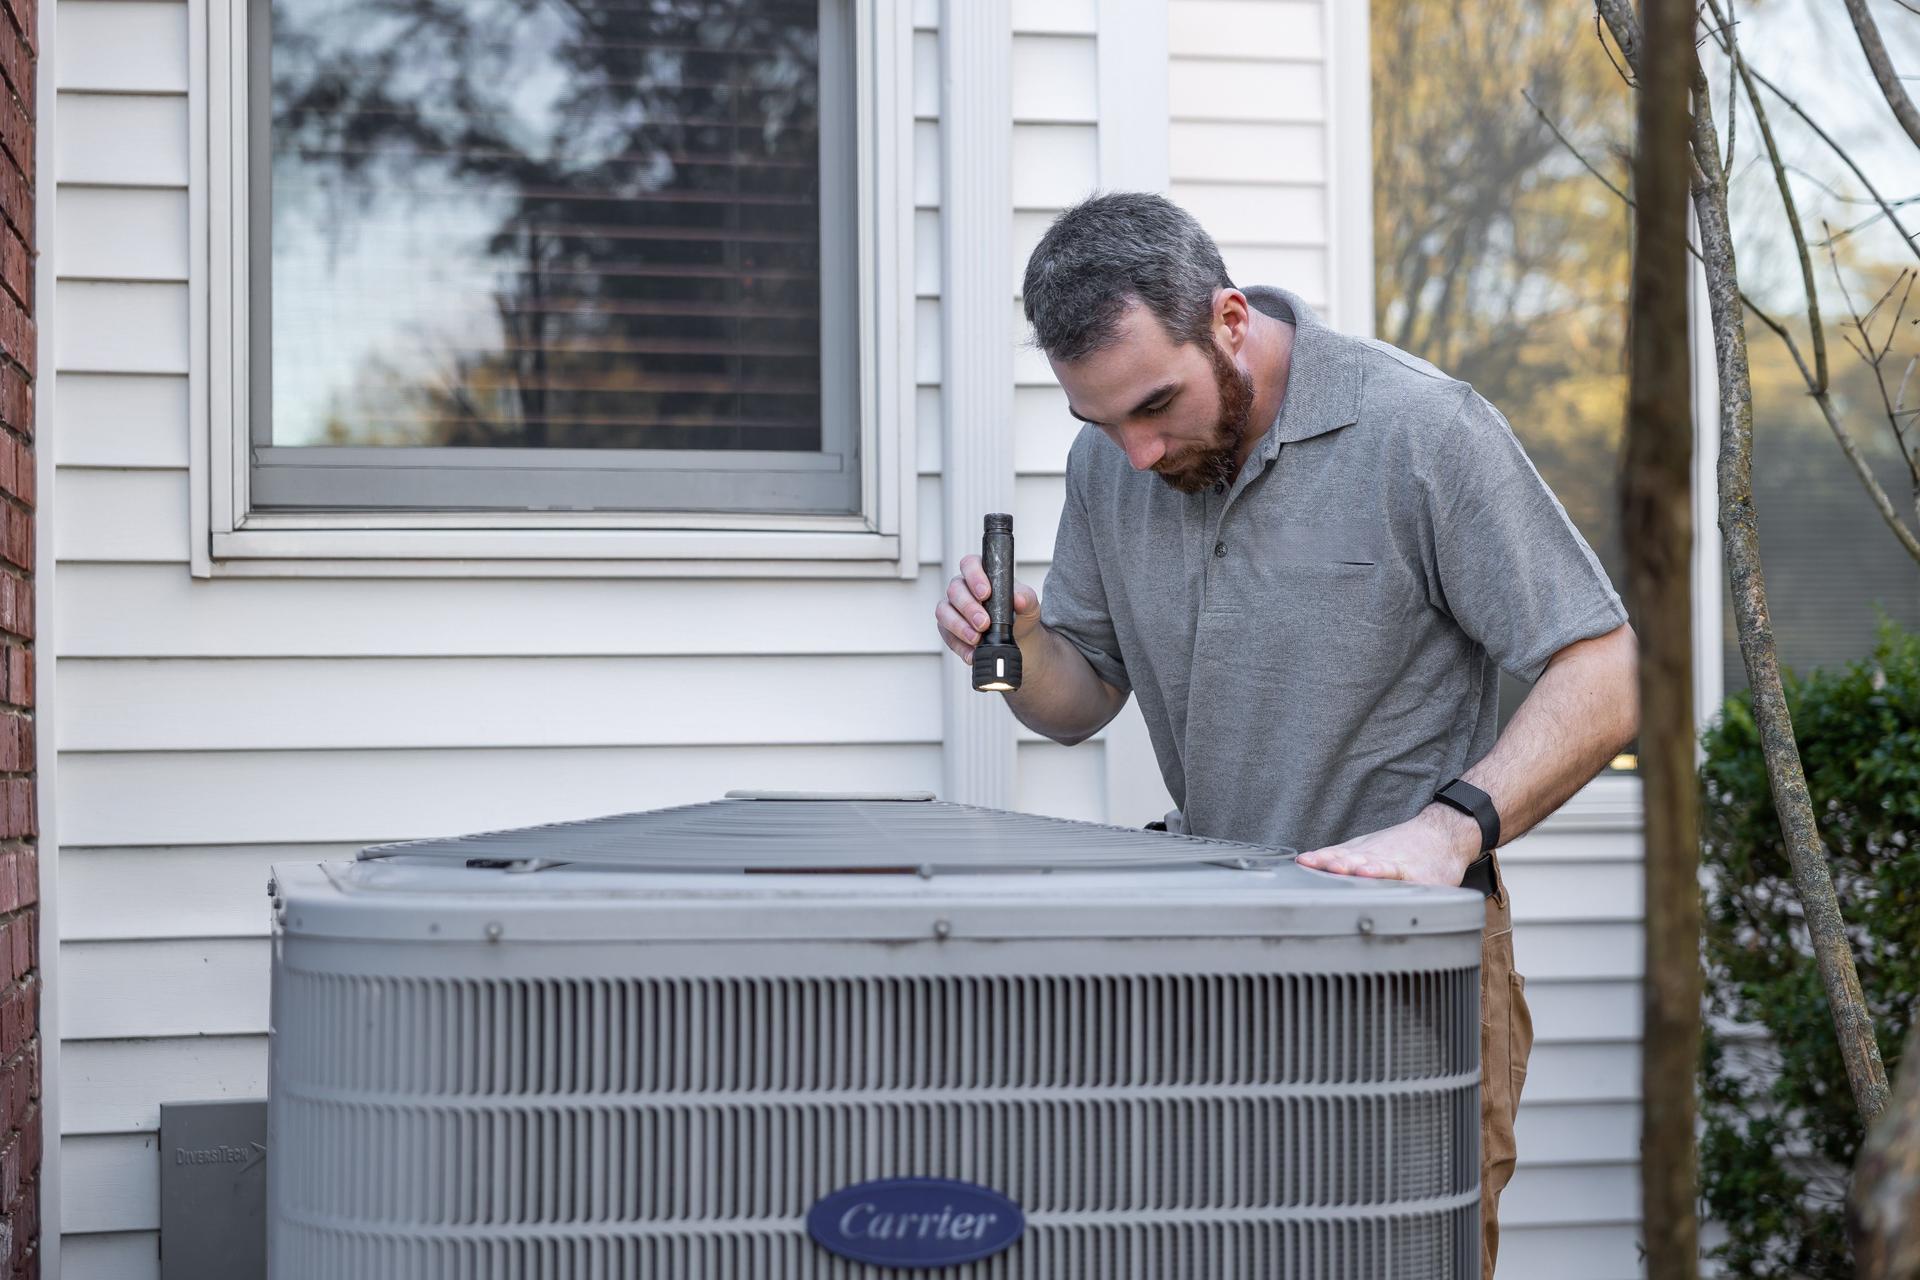
The inspection and investigation period is essential. This is your designated window to schedule professional inspections, confirm school district information, verify internet availability, and complete any other due diligence that matters to you. The checklist should reflect your specific priorities.
We have several local professional inspection companies that we trust to help you inspect the property.
A general inspection usually covers:
- Structural components
- Electrical
- Plumbing
- HVAC
- Roof
- Foundation
BUT there are several additional items you can add on, such as:
- Well and septic inspection
- Land survey (always recommended)
- Sewer line camera scope
- Radon testing
- Air mold testing
- Outbuilding inspections
- Termite inspection
Keep in mind, that unless you are purchasing a newly constructed home, you are buying a USED property. There will be all sorts of little things that need updating. For negotiation purposes, we are really keeping an eye out for any major health or safety concerns.
This isn’t about finding a “perfect” house — it’s about understanding what you’re buying and negotiating accordingly.
Sometimes you ask for repairs. Sometimes you ask for credits. Sometimes you walk away.
We’re here no matter what path you take.
7. Appraisal, Title Work, Loan Final Approval & Walk Through
Your lender will order an appraisal to confirm the home’s value matches the purchase price. Your title company will do a search to make sure the home is free from liens and encumbrances and will disclose any recorded easements.
From there:
- Underwriting signs off
- Final loan documents are prepared
- You receive your Closing Disclosure
- We conduct a final walk through of the property to confirm contractually agreed upon items are in place
You’re almost there. Can you hear the keys clinking?
8. Closing Day
Bring the moolah!
You sign the documents.
You get the keys. (Depending on the possession agreement)
You officially become a homeowner.
And yes — it feels as good as you imagine.
What First-Time Buyers Should Really Know
You don’t need 20% down or perfect credit.
You don’t need to know everything, that’s our job.
The right guidance can save you thousands.
Buying a home is both emotional and financial, and we protect both sides.
The biggest mistake first-time buyers make? Waiting because they think they need to “have it all figured out.” Our market has continued to grow in value. Now is always the best time to buy. They aren’t making any more of that land stuff…You just need the right starting point.
 Listing information is provided by Participants of the MichRIC MLS. IDX information is provided exclusively for personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information deemed reliable but not guaranteed. ©: MichRIC MLS. Last Update September 21, 2026 2:15 PM UTC
